First day cover ·
Five Financial Steps for Families Facing Cognitive Decline
Early conversations, current documents and a flexible care plan can help families protect a loved one’s wishes and prepare for changing needs.
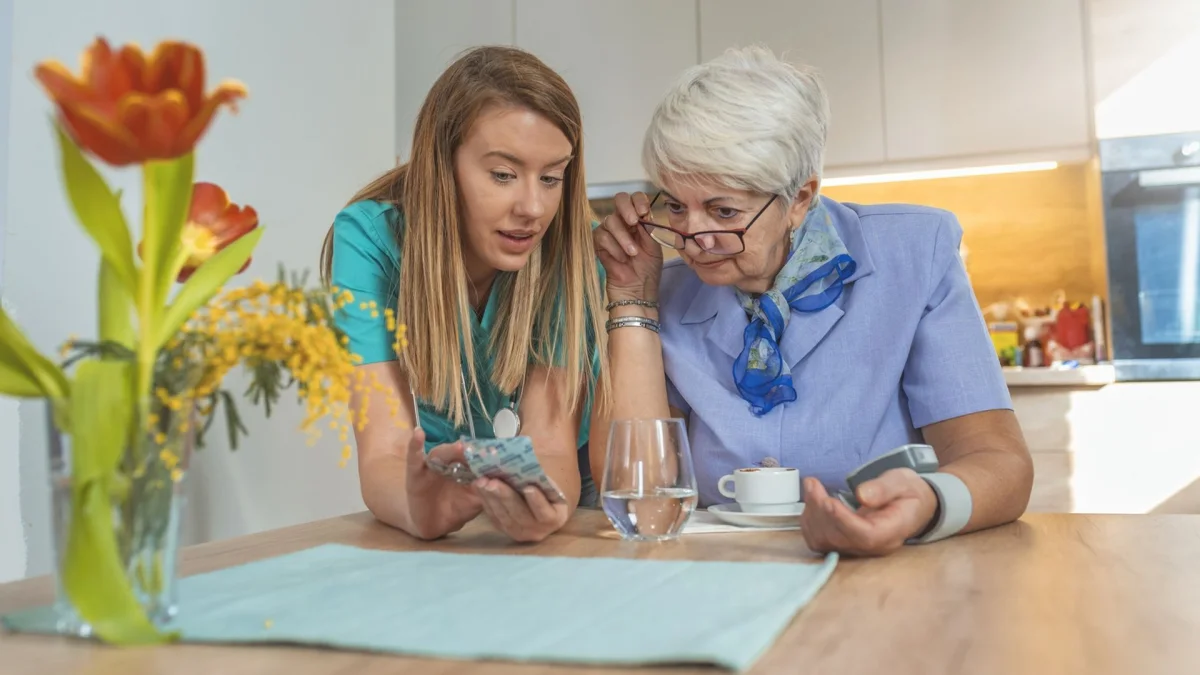
When someone starts repeating questions, missing bill payments or losing track of appointments, medical care is only part of the family’s response. Financial decisions can also become time-sensitive: without clear records and the right documents, loved ones may struggle to manage money or put the person’s wishes into practice.
A useful plan starts with the person’s priorities and current financial picture, then connects family members with trusted medical, legal and financial professionals. It can’t predict how health or care needs will change. It can give families a clearer way to make decisions as they arise.
Start with the full picture
Begin by gathering information about income and expenses, insurance coverage, accounts, legal documents, living arrangements and the people available to help. A physical and cognitive evaluation can inform the process, but it won’t answer every practical question about paying bills, arranging care or managing a household.
Build a care team that reflects the needs of the person and family. That may include close relatives or friends, a physician, a financial adviser and an attorney. Agreeing early on who can help with which decisions makes it easier to coordinate when circumstances change.
The process can feel daunting, especially when families don’t yet know how much support will be needed. Still, having a clearer picture can help surface gaps before a decision becomes urgent. A financial adviser may help organize the financial details alongside the rest of the care team.
Ask what independence means to them
Families may assume that staying at home is the person’s main goal, but preferences vary. They might value being near relatives, keeping a social routine, avoiding home maintenance or remaining in familiar surroundings. Early conversations with aging parents can help clarify those priorities while the person can express them.
Then check whether the available resources support the preferred arrangement. Staying at home may involve modifications, paid help or ongoing support. Those expenses can change the comparison with other care arrangements; aging in place isn’t automatically less costly.
It helps to separate a person’s preference from assumptions about what will be affordable or practical. The family can discuss both, then revisit the plan as needs and resources become clearer.
Put authority and wishes in writing
Conversations establish what someone wants. Current documents help others act on those wishes if the person can no longer manage decisions independently. Review healthcare and financial powers of attorney, advance directives, beneficiary designations and account records with the person and relevant professionals. Confirm that the information is current and that the intended decision-makers are clearly identified.
Putting off paperwork can leave relatives unsure who has authority to handle a financial or healthcare matter. A person may have clear preferences but still be unable to carry them out without the appropriate documents. An registered investment adviser (RIA), Certified Financial Planner (CFP), certified public accountant (CPA) or estate attorney may help review the parts of the plan within their expertise. The article’s contributor participates in Kiplinger’s Adviser Intel program, a network of financial professionals who share advice on wealth building and preservation.
Plan for daily care and its costs
Practical support may include home modifications, transportation alternatives, meal delivery or companion care. These measures can help address everyday risks, such as falls, missed medication or financial exploitation, while allowing the family to respond to the person’s needs.
Care costs also need a close look. Health coverage and long-term custodial care are different things. Medicare may cover medically necessary services, while day-to-day help with bathing, dressing, preparing and eating meals, or medication reminders generally falls outside that coverage and is usually paid out of pocket. Reviewing likely costs, insurance benefits and personal resources before this care becomes urgent can help families prepare for the expense.
For broader context on cognitive decline and finances, or the relationship between dementia risk and retirement, families can explore these related resources. The practical needs in each situation will differ, so the plan should reflect the person’s circumstances.
Review the plan as circumstances change
A plan that fits today may not fit in five or 10 years. Health needs, family relationships and the suitability of a home or care arrangement can all change. Planning ahead doesn’t mean locking the family into one course. It means checking periodically that the arrangements still match the person’s wishes and available resources.
Families often have an easier time making these decisions when conversations begin before a crisis. Start at home with the people closest to the person, then bring in medical, legal and financial professionals who can help address the questions that arise. For additional reading, see ways to start a conversation about parents’ finances, a guide to caring for aging parents, an adviser’s experience preparing for changing needs, a look at family financial roles and advice on easing the strain of care.
The aim isn’t to settle every future question at once. It’s to make the person’s wishes easier to understand, keep authority and records current, and leave room to adapt as care needs evolve.
The source article was written by a contributing adviser and presents that adviser’s views rather than the publication’s editorial staff. Adviser records can be checked through the SEC or FINRA. Readers can also sign up for the free, twice-weekly Adviser Intel newsletter.
===END===